Running a business in Everett means facing real risks-from liability lawsuits to property damage to accidents on the job. Without proper coverage, one incident can drain your savings and threaten everything you’ve built.
At Top Insurance Associates, a Trucordia Business, we help Everett business owners find small business insurance that actually protects what matters. This guide walks you through the coverage types you need, how to compare providers, and how to build a safety net for your company’s future.
Why Your Everett Business Needs Insurance Protection
Everett businesses face exposure to lawsuits that can cost tens of thousands of dollars in legal fees alone, even if the claim gets dismissed. A single liability verdict can exceed your annual profits. Property damage compounds this risk-Everett’s industrial zones and coastal weather patterns create exposure to fire, theft, and weather-related losses. Unexpected events like key employee injuries or supply chain disruptions can halt operations entirely. Most small businesses cannot absorb even moderate losses and stay afloat without financial reserves built specifically for these gaps.
Liability claims drain business reserves fast
A customer injured on your premises, a product defect, or an accident involving your company vehicle creates immediate legal liability. General liability insurance covers medical bills, legal defense costs, and settlements-expenses that would otherwise come directly from your operating account. Everett’s retail and service sectors face this exposure constantly, where customer interactions happen throughout each day. Workers compensation is equally non-negotiable; Washington State requires it for any business with employees.
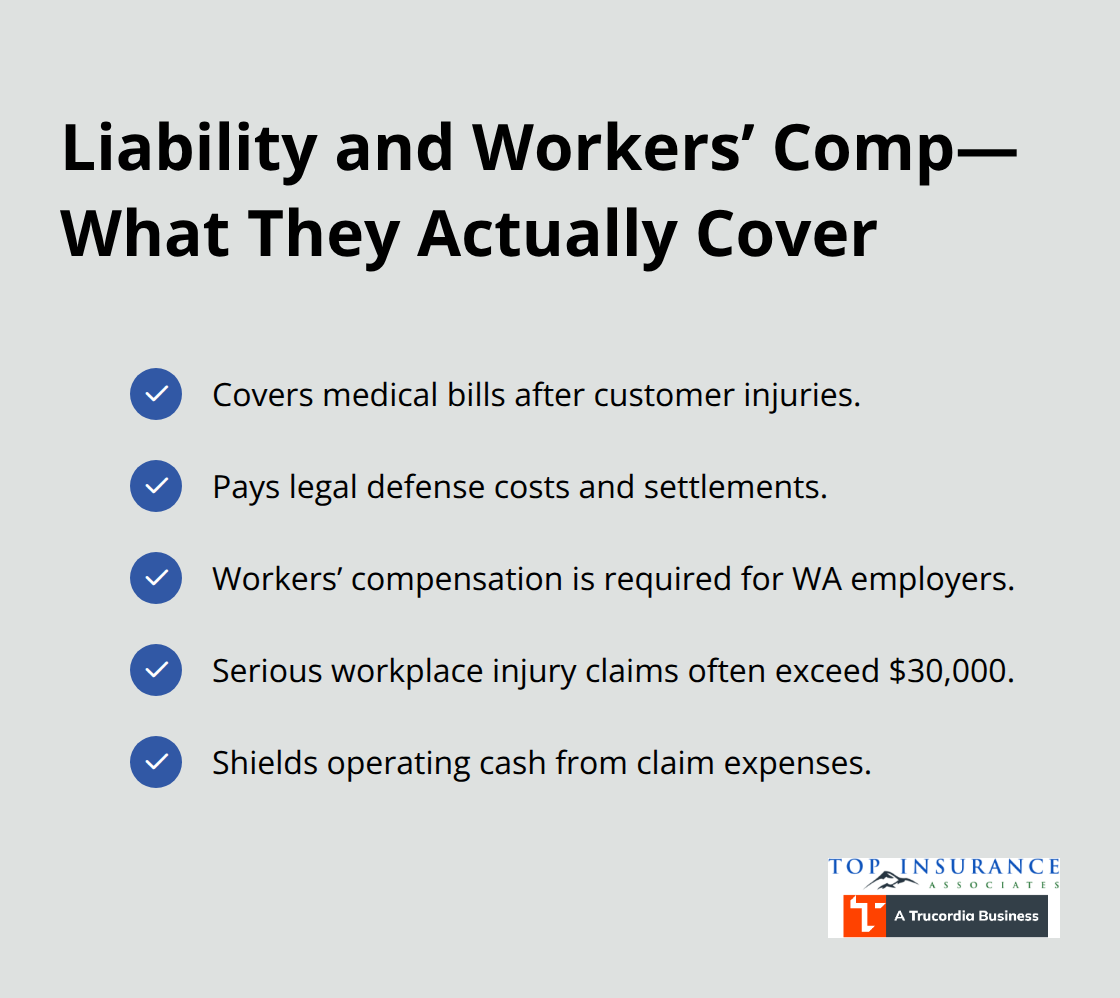
Medical costs for workplace injuries routinely exceed $30,000 for serious cases, making this coverage economically essential rather than optional.
Property and asset coverage protects your physical investment
Your building, equipment, inventory, and vehicles represent years of capital investment. Fire, theft, weather damage, and vandalism threaten these assets daily. Replacing a commercial HVAC system costs $5,000 to $15,000; a total building loss can exceed hundreds of thousands. Business interruption coverage, often bundled with property insurance, replaces lost income while you rebuild-a protection that many Everett business owners overlook. You lose revenue during downtime while still facing rent, payroll, and loan obligations without this layer. Accurately calculating replacement costs matters, since underinsurance leaves dangerous gaps in your protection.
Selecting the right coverage requires local expertise
Everett’s specific business environment-from waterfront operations to manufacturing facilities to service-based companies-creates distinct insurance needs that generic policies miss. An independent agent who understands Everett’s local risks can match your actual exposure to appropriate coverage limits and policy types. This personalized approach prevents both overinsurance (wasting premium dollars) and underinsurance (leaving gaps that cost far more when claims happen). The next section walks through the specific insurance types that protect Everett businesses most effectively.
Coverage Types That Actually Protect Everett Businesses
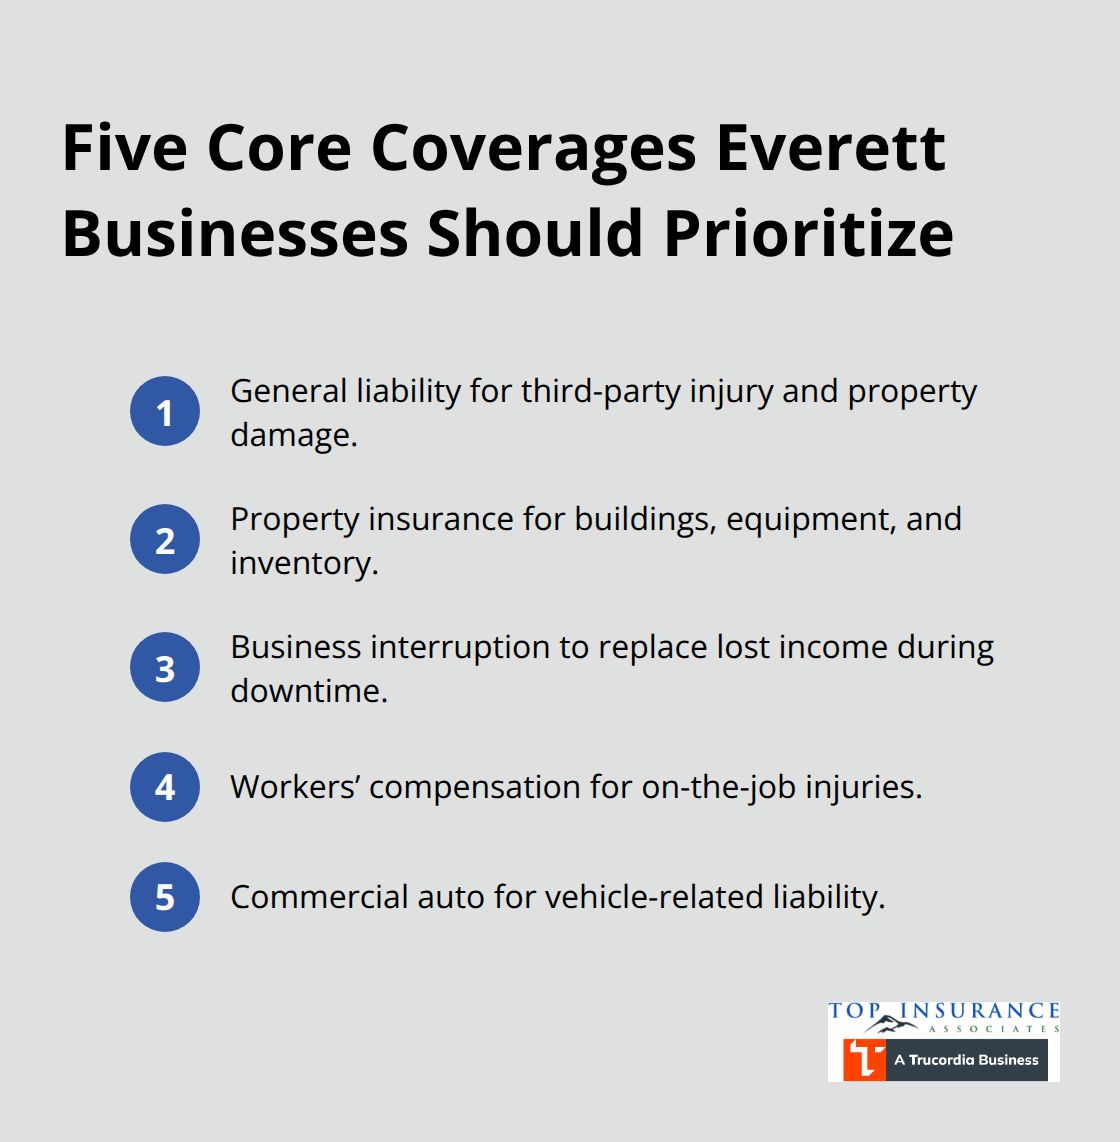
General liability insurance forms the foundation for any Everett business operating in retail, services, or manufacturing. This coverage pays for bodily injury and property damage claims when a customer, vendor, or third party gets hurt on your property or from your business operations. Everett’s service and retail sectors face constant exposure-a customer slipping in your store, a contractor accidentally damaging client property, or a product defect triggering a lawsuit. Most commercial general liability policies in Washington start at annual premiums between $400 and $1,500 depending on your business type and revenue, making this the most cost-effective risk transfer available. Policy limits matter significantly; we recommend minimum coverage of $1 million per occurrence and $2 million aggregate for most small businesses, since single incidents regularly exceed $500,000 in damages.
Property insurance protects your physical assets from real threats
Property damage claims destroy unprepared businesses faster than liability does. Your building, equipment, inventory, and vehicles represent concentrated capital that fire, theft, weather, or vandalism can eliminate entirely. Everett’s coastal location and industrial zones create specific exposure-wind damage, salt spray corrosion, and theft in less-secure areas happen regularly. A typical small commercial building replacement cost runs $150 to $300 per square foot, meaning a 5,000 square foot facility could cost $750,000 to $1.5 million to rebuild. Business interruption coverage, bundled with property insurance, replaces lost income while you rebuild-a protection most Everett owners underestimate. Without it, you still pay rent, utilities, payroll, and loan payments while generating zero revenue, typically lasting 30 to 90 days minimum. Calculate replacement costs accurately rather than guessing; underinsured properties leave dangerous gaps that cost exponentially more when claims happen.
Workers compensation protects your employees and your business
Washington State mandates workers compensation insurance for any business with employees, and the penalties for non-compliance include fines up to $1,000 per day plus criminal prosecution. This coverage protects both your workers and your company’s financial stability when accidents occur on the job. Everett’s manufacturing and industrial operations create heightened exposure to serious injuries that can generate substantial claims.
Commercial auto insurance covers vehicle-related liability
Commercial auto insurance is non-negotiable if your business operates any vehicles-personal auto policies explicitly exclude business use and leave you personally liable for accidents. Everett’s traffic patterns and industrial operations create constant vehicle exposure, making commercial auto coverage economically essential rather than optional. This protection extends to all business-related driving, whether employees use company vehicles or their own cars for work purposes.
Choosing the right coverage limits for your situation
Coverage limits determine how much your insurance actually protects when claims happen. Underestimating your exposure leaves gaps that cost far more than higher premiums would. Everett’s specific business environment-from waterfront operations to manufacturing facilities to service-based companies-creates distinct insurance needs that generic policies miss. An independent agent who understands Everett’s local risks can match your actual exposure to appropriate coverage limits and policy types. This personalized approach prevents both overinsurance (wasting premium dollars) and underinsurance (leaving gaps that cost far more when claims happen). Top Insurance Associates, a Trucordia Business, compares options across multiple carriers to help Everett business owners find coverage that fits their actual needs and budget. The next section walks through how to select the right provider and coverage combination for your company.
Finding the Right Insurance Partner in Everett
Selecting an insurance provider matters more than most Everett business owners realize, because the wrong choice leaves you either overpaying for unnecessary coverage or discovering gaps when claims actually happen. Insurance companies operate with vastly different underwriting standards, claims handling speed, and pricing models-meaning two policies that look identical on paper can deliver completely different results when your business needs them most. Everett’s specific business environment demands a provider who understands local risks, from waterfront operations to manufacturing facilities to service-based companies, rather than applying generic coverage formulas that miss your actual exposure. An independent insurance agency that represents multiple carriers gives you access to competitive quotes and the expertise to match your specific situation to appropriate coverage, rather than forcing you into one company’s standard offerings.
Multiple carriers mean real savings and better coverage fits
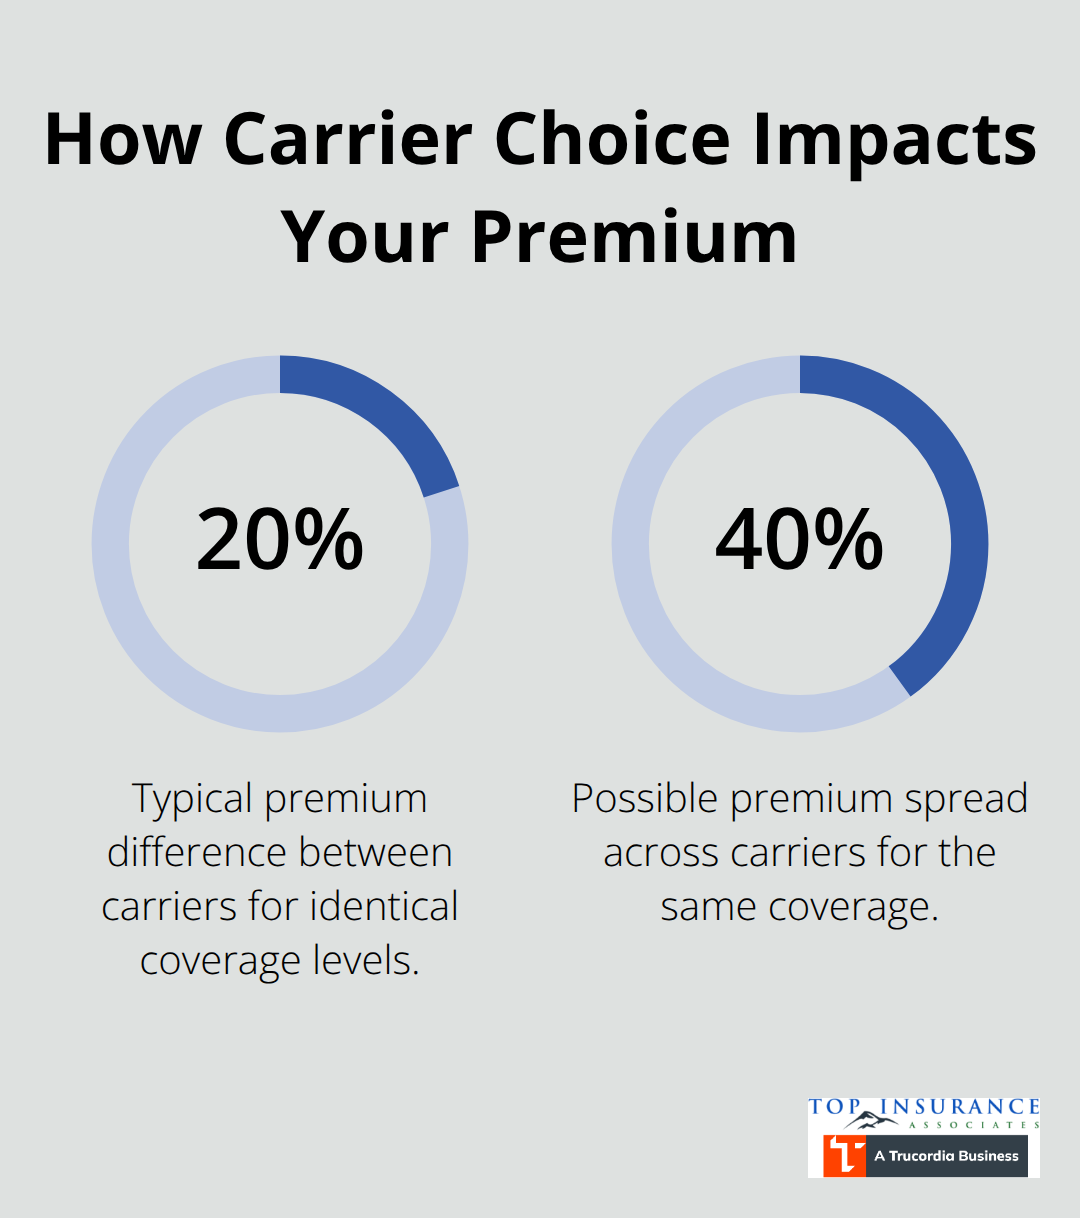
Shopping a single insurance company wastes money because each carrier prices risk differently and offers distinct policy features. One company might excel at covering manufacturing operations while another specializes in retail businesses, creating premium differences of 20 to 40 percent for identical coverage levels. Getting quotes from at least three different carriers takes roughly two hours of your time but typically saves $1,500 to $3,000 annually for small businesses-a return that justifies the effort immediately.
When you work with an independent agency rather than calling companies directly, you avoid the sales pressure and incomplete information that captive agents provide, since independent agents have no financial incentive to push one company over another.
Local knowledge prevents costly coverage mistakes
An agent who understands Everett’s specific business environment catches exposure gaps that national insurance companies miss entirely. Waterfront businesses face salt spray corrosion and flood exposure; manufacturing facilities need equipment breakdown coverage; service-based companies need higher liability limits than retail operations. A provider unfamiliar with these local factors might recommend standard limits that leave you significantly underinsured when claims happen. Claims handling speed matters as much as coverage itself-some carriers take 30 days to process straightforward claims while others complete them in three days, creating cash flow stress when your business is already disrupted. Asking potential providers about their average claims resolution time reveals whether they prioritize speed or use delays as a profit strategy. An independent agent with established relationships at multiple carriers can often expedite claims processing and advocate for you when disputes arise, something you cannot accomplish calling a 1-800 number.
Independent agencies deliver personalized service for Everett businesses
Top Insurance Associates, a Trucordia Business, compares options across multiple carriers to help Everett business owners find competitive protection without overpaying. An independent agency in Everett, WA that represents multiple carriers provides local, personalized service for quotes, policy reviews, and claims support-delivering the expertise and advocacy that national companies cannot match. This approach prevents both overinsurance (wasting premium dollars) and underinsurance (leaving gaps that cost far more when claims happen).
Final Thoughts
Protecting your Everett business requires more than hoping nothing goes wrong. The risks are real-liability lawsuits, property damage, employee injuries, and vehicle accidents happen to businesses every day, and one uninsured incident can destroy years of work. Small business insurance in Everett isn’t an expense to minimize; it’s a financial foundation that lets you operate without fear of catastrophic loss.
Your specific situation depends on your industry, location, revenue, and assets. A manufacturing facility faces different exposure than a retail store; a waterfront operation needs different coverage than an office-based service company. Generic policies miss these distinctions, leaving you either overpaying for unnecessary coverage or discovering dangerous gaps when claims actually happen.
Shopping multiple carriers typically saves $1,500 to $3,000 annually for small businesses, and an independent agency gives you access to competitive quotes without sales pressure. Contact Top Insurance Associates, a Trucordia Business to discuss your specific coverage needs and get quotes from carriers that actually fit your business. Building long-term financial stability starts with protection that covers your real exposure, not generic formulas that miss what matters most.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.