Standard home insurance falls short when you own a luxury residence. High value home insurance bridges those gaps with coverage limits and specialized protections that match what your property is actually worth.
We at Top Insurance Associates, a Trucordia Business help homeowners understand why this distinction matters and what options exist for their high-end properties.
What Sets Luxury Home Insurance Apart
Standard homeowners policies max out at coverage limits that simply don’t match what luxury properties cost to replace. Most conventional policies cap dwelling coverage around $300,000 to $500,000, which falls drastically short for high-end residences. A luxury home in a desirable location often costs $1 million to $5 million or more to rebuild, meaning standard coverage leaves you exposed to massive financial loss. High value home insurance removes these artificial ceilings, offering dwelling limits that scale to what your property actually requires.
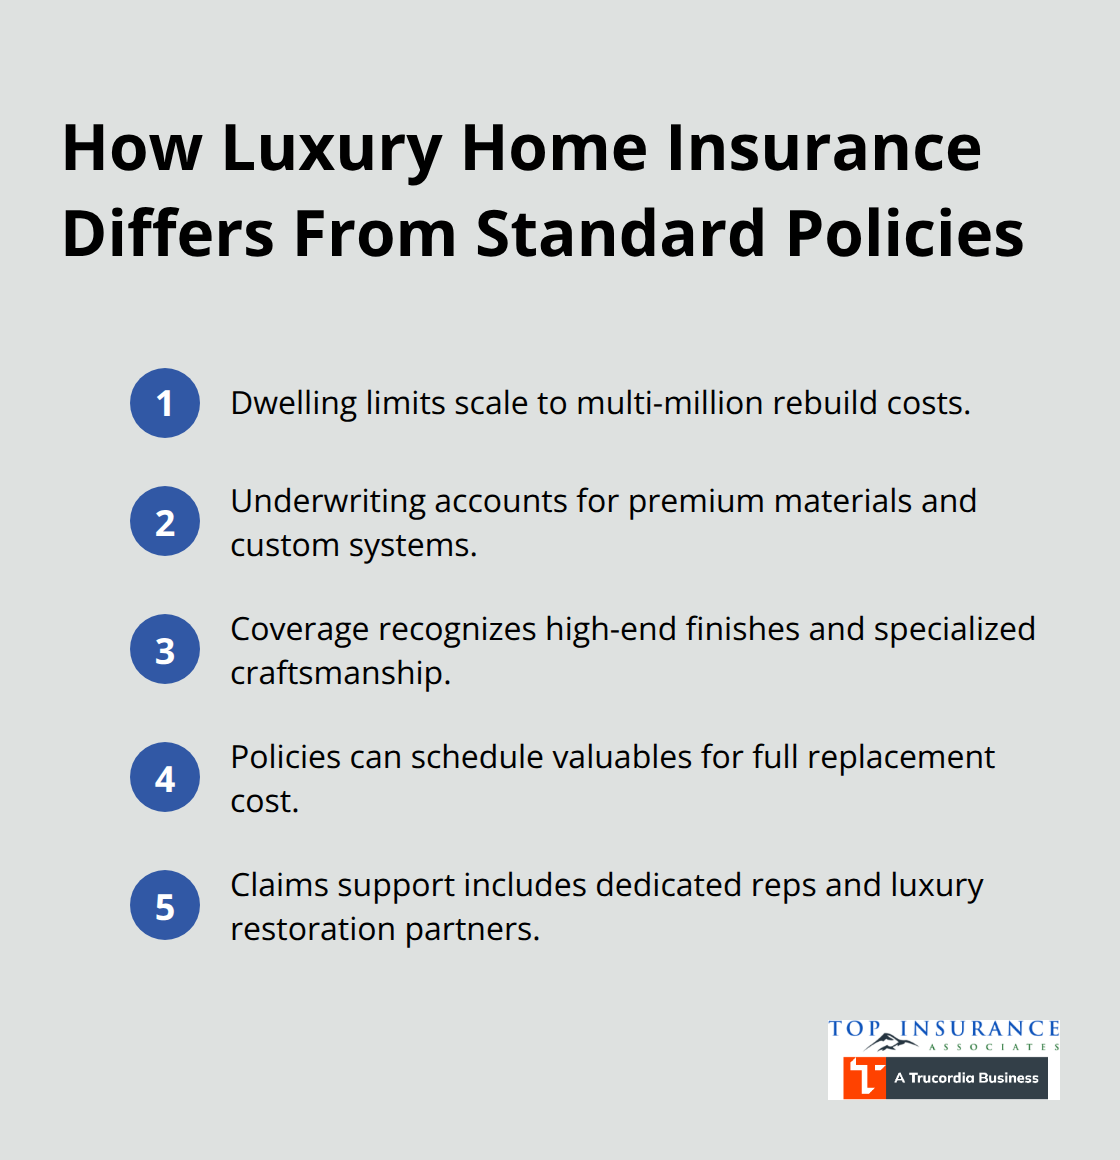
Standard insurers use one-size-fits-all underwriting that ignores the premium materials, custom construction, and specialized systems found in luxury homes.
Protecting What Makes Your Home Valuable
High-end finishes and features demand protection that goes beyond generic coverage language. A luxury home typically includes marble countertops, hardwood flooring, smart home automation, wine cellars, home gyms, and architectural details that cost far more to replace than standard materials. Standard policies often exclude or severely limit coverage for these elements, treating them as ordinary construction when they clearly are not. High value policies specifically account for granite, imported tile, custom cabinetry, and architectural features that require specialized contractors and materials sourcing.
Jewelry, fine art, and collectibles face even worse treatment under standard policies, typically limited to $1,500 to $2,500 total coverage regardless of actual value. Specialized high value policies allow you to schedule these items individually with full replacement cost coverage, backed by appraisals that document their actual worth. Your $50,000 painting or $30,000 jewelry collection receives proper protection instead of facing arbitrary caps.
The Claims Experience Separates Good from Inadequate
When a luxury home suffers damage, the claims process becomes far more complex than filing for standard property loss. A water event in a high-end home requires specialized restoration companies, coordinated work across multiple contractors, and weeks of temporary relocation while custom elements are rebuilt or restored. Standard insurers often assign claims adjusters with experience handling $200,000 homes, not $2 million properties with unique construction and materials.
High value insurers maintain relationships with specialized contractors and restoration companies who understand luxury home requirements. They also provide dedicated claims representatives who remain accessible throughout the process rather than routing you through call centers. This matters significantly when your claim involves coordinating restoration of imported materials, matching custom finishes, or replacing irreplaceable architectural elements that require craftspeople with specific expertise.
Coverage Limits That Actually Protect Your Investment
Your luxury home’s true replacement cost extends far beyond the structure itself. High value policies account for the actual expenses involved in rebuilding-not the depreciated or discounted figures that standard insurers calculate. When you own a property worth $2 million or more, the difference between standard coverage limits and high value limits translates directly to out-of-pocket losses you would absorb yourself.
An independent insurance agency can help you evaluate what your specific property actually requires. They compare options across multiple carriers to find policies that match your home’s unique characteristics and location. This approach (comparing multiple insurers rather than accepting one standard quote) often reveals significant gaps in coverage that you wouldn’t catch on your own.
Coverage Limits That Match Your Luxury Home’s True Value
Rebuilding a luxury home costs far more than most homeowners realize, and standard replacement cost calculations severely underestimate these expenses. When a $3 million home suffers major damage, the actual reconstruction often exceeds the original purchase price because labor, materials, and specialized trades have increased since construction. Dwelling coverage in high value policies starts at $1 million and scales upward to $10 million or beyond, matching what your property would genuinely cost to rebuild from the ground up. Obtaining a detailed reconstruction estimate from a qualified contractor before selecting your coverage limit prevents the catastrophic mistake of underinsuring by hundreds of thousands of dollars. Standard policies calculate replacement cost using depreciation formulas that assume generic materials and labor rates; luxury homes with imported marble, custom millwork, and specialized HVAC systems require 20 to 40 percent higher reconstruction budgets than these formulas generate.
Temporary Housing Costs During Extended Restoration
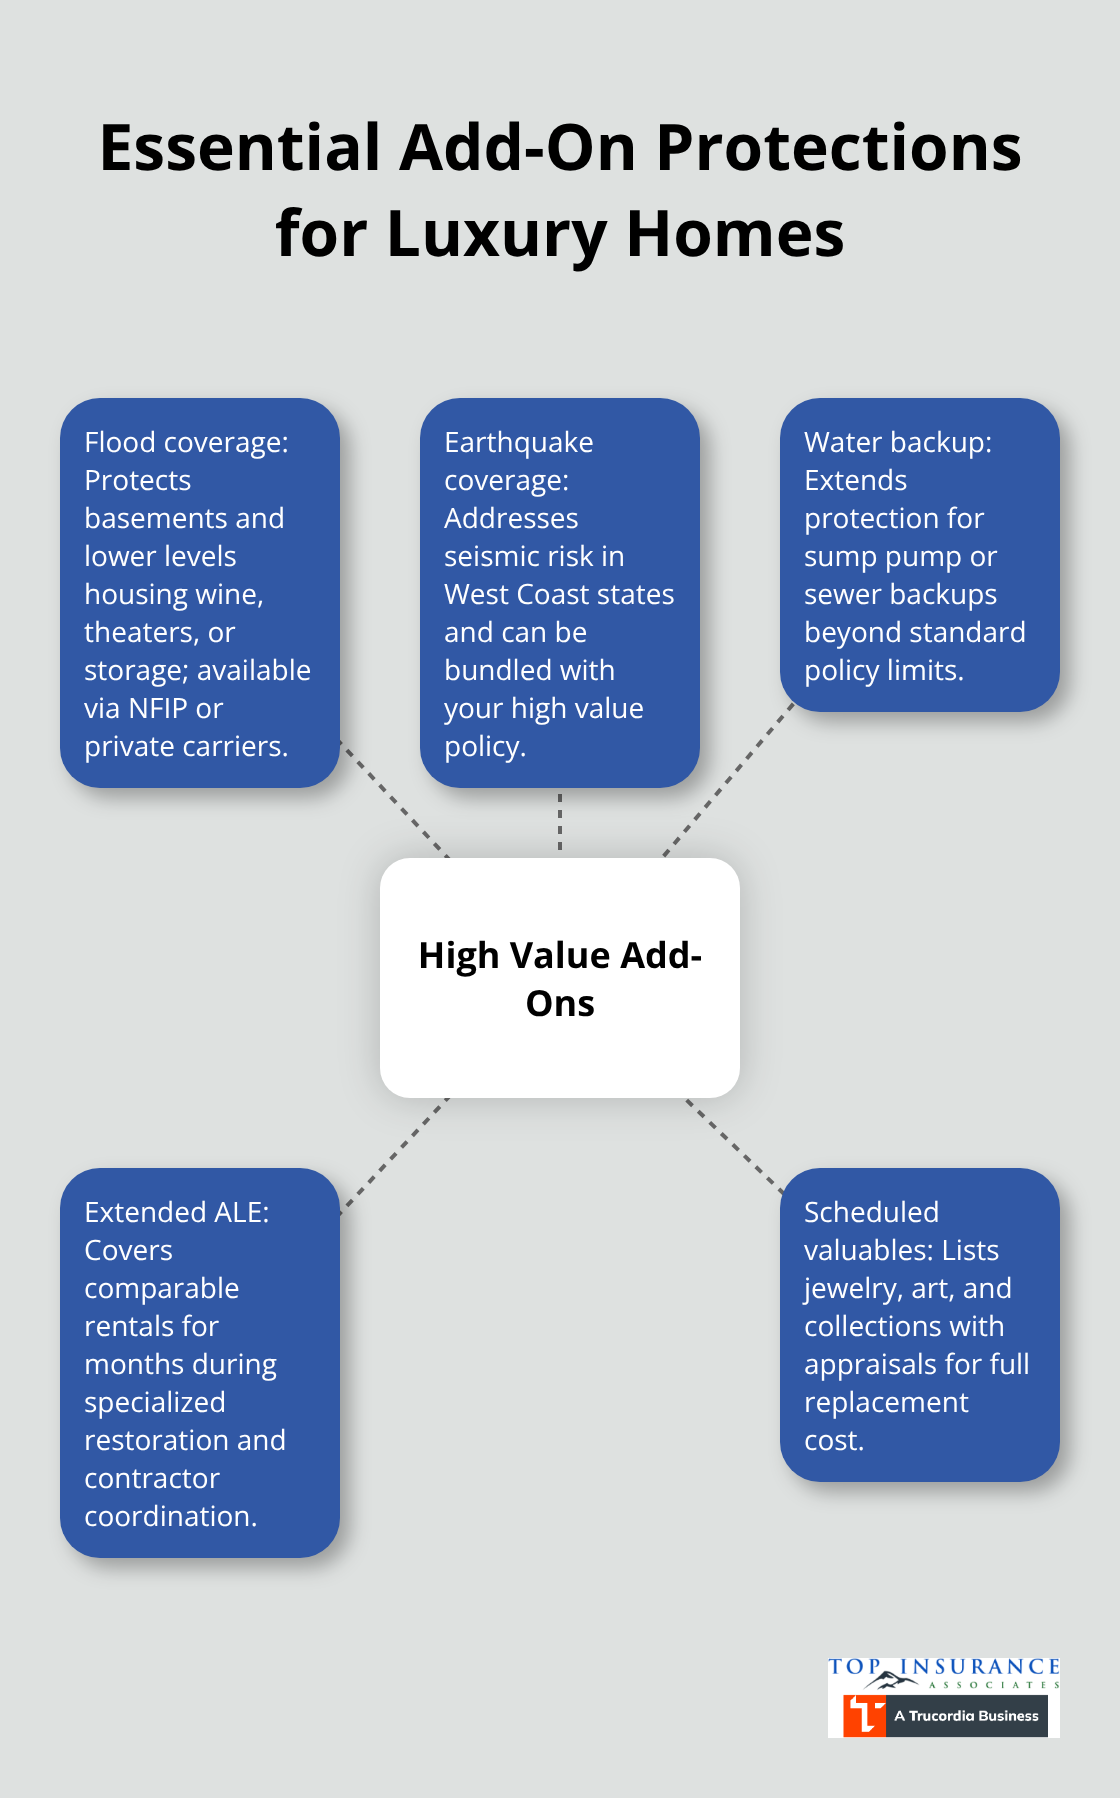
Temporary housing after a significant loss at a luxury property often means renting comparable accommodations, which can cost $10,000 to $25,000 monthly in high-value markets. Standard policies typically cap additional living expenses at 20 to 30 percent of dwelling coverage, creating severe shortfalls when your family needs months of temporary housing while restoration work proceeds. High value policies increase this percentage significantly and remove artificial caps, recognizing that restoring custom elements, coordinating specialized contractors, and sourcing imported materials extends timelines far beyond what standard properties experience. A water event affecting your home’s custom wine cellar, smart home systems, and imported finishes might require 90 to 180 days of professional restoration work, making adequate temporary housing coverage non-negotiable. Confirm that your policy specifically addresses extended displacement scenarios and that the monthly limits actually match rental costs in your area-this prevents discovering coverage shortfalls when you need housing most.
Water Damage Protection Beyond Standard Exclusions
Water damage represents the leading cause of homeowner insurance claims, with average water damage claims exceeding $11,000 according to the Insurance Information Institute, yet standard policies exclude damage from flooding and often limit water backup coverage. Luxury homes with basements containing wine collections, home theaters, or valuable storage face exponential loss potential when water damage occurs, making flood insurance through the National Flood Insurance Program or private flood carriers absolutely necessary if your property sits in any flood zone. High value policies allow you to add flood coverage without the restrictive terms that plague standard policies, and these additions cost significantly less when purchased together with your primary high value home policy than when purchased separately.
Earthquake Coverage for Properties in Seismic Zones
Earthquake coverage operates similarly to flood protection-standard policies exclude earthquake damage entirely, leaving West Coast luxury homeowners completely unprotected despite the genuine risk in regions like Washington, California, and Oregon. High value policies allow you to add earthquake coverage without the restrictive terms that plague standard policies. Comparing standalone flood insurance against coverage bundled with your high value home package often reveals savings of 15 to 30 percent on combined premiums, making the bundled approach financially superior for most luxury homeowners.
Your property’s location, construction materials, and specific features determine which additional protections matter most. An independent insurance agency can help you evaluate water, earthquake, and flood risks specific to your address and recommend coverage options that match your actual exposure.
Where Standard Policies Fall Short for Luxury Homes
Most homeowners discover coverage gaps only after a loss occurs, and luxury property owners face far steeper consequences when this happens. Standard policies underinsure high-value homes systematically because insurers use replacement cost formulas designed for average properties selling between $300,000 and $500,000. When your home costs $2 million or $3 million to rebuild, these formulas produce coverage limits that leave you exposed to six-figure out-of-pocket losses. Approximately 40 percent of homeowners underestimate their property’s replacement cost, but this statistic masks a far worse problem for luxury homeowners-their underestimation typically reaches hundreds of thousands of dollars rather than tens of thousands. A $3 million luxury home with $1.5 million in standard coverage means you absorb $1.5 million in losses yourself, a scenario that becomes financially catastrophic when a major event strikes.
An independent appraisal from a contractor who specializes in luxury home reconstruction costs nothing compared to the protection it provides, yet most luxury homeowners never obtain one before selecting coverage limits.
Fine Art, Jewelry, and Collectibles Face Arbitrary Caps
Standard homeowners policies treat your $80,000 art collection the same way they treat your furniture-capping total coverage at $1,500 to $2,500 regardless of actual value. This limitation applies to all jewelry, watches, fine art, and collectibles combined, meaning if a fire destroys both your jewelry and your paintings, you split that inadequate cap between them. Scheduled personal property endorsements through high value policies eliminate these artificial restrictions entirely by allowing you to list specific items with individual coverage limits backed by professional appraisals. The cost of scheduling items typically runs $50 to $150 annually per item depending on the carrier and coverage amount, a negligible expense compared to losing an irreplaceable collection to an arbitrary policy limit.
Secondary Properties and Rental Arrangements Create Coverage Voids
Standard policies exclude or severely restrict coverage for secondary properties, vacation homes, and any arrangement involving rental income or short-term guest stays. If you own a beach house, mountain cabin, or investment property alongside your primary residence, standard policies either decline coverage entirely or charge substantially higher premiums with restrictive terms. High value insurers recognize that affluent homeowners commonly own multiple properties and maintain flexible coverage options that account for this reality. Short-term rental properties face particular challenges under standard policies because insurers categorize them as commercial operations rather than residential properties, triggering exclusions and requiring separate commercial coverage that costs significantly more than residential alternatives. Experienced insurers help luxury homeowners identify which properties fall outside their current coverage and recommend solutions that protect each location without forcing you into expensive commercial policies that overcharge for residential-use situations.
Final Thoughts
Luxury homeowners face a straightforward choice: accept the financial exposure that comes with standard home insurance, or invest in high value home insurance that actually protects what you own. The gap between standard coverage and what your property costs to rebuild isn’t theoretical-it’s the difference between absorbing a six-figure loss yourself or having your insurer cover it. Standard policies systematically underinsure luxury properties because they use formulas designed for homes worth a fraction of what yours actually costs to replace.
Working with an independent insurance agency makes the difference between generic coverage and protection tailored to your specific situation. We at Top Insurance Associates, a Trucordia Business compare options across multiple carriers to find coverage that matches your home’s unique characteristics, location, and contents. Whether you own a primary residence worth millions, maintain secondary properties, or rent out vacation homes seasonally, we identify gaps in your current coverage and recommend solutions that fit your actual needs.
Start by obtaining a detailed reconstruction estimate from a contractor who specializes in luxury home rebuilding costs (this single step prevents the catastrophic mistake of underinsuring by hundreds of thousands of dollars). Next, schedule a comprehensive policy review with an independent agent who can evaluate your dwelling coverage, additional living expenses, water damage protection, and personal property limits against what your property actually requires. Contact Top Insurance Associates, a Trucordia Business to discuss your high value home insurance needs.
Disclaimer: The information provided in this blog is for general informational purposes only and does not constitute legal, financial, or insurance advice. Coverage options, terms, and availability may vary. Please consult with a licensed professional for advice specific to your situation. Artificial intelligence may have been used to generate text and images in some blog articles.